A free credit report is one of the few money tools that costs nothing, and I avoided mine for years anyway. I was sure it would be a wall of red. It wasn’t. It was mostly boring, with two lines that were wrong.
If you’ve been putting this off because you’re scared of what’s in there, I get it. I was carrying credit card debt that would eventually add up to $14,000 when I finally looked. Below is where to get your reports without paying a cent, how to read them, how to fix a mistake, and which “free” sites want your card number. My experience plus a lot of FTC and CFPB reading, not financial advice.
Where to get your free credit report (there’s only one official door)
A search brings up a dozen sites with “free” in the name. The real one is a single central system for the three nationwide bureaus: Equifax, Experian and TransUnion.
According to the FTC’s page on free credit reports, there are only three ways to order them:
- Online at AnnualCreditReport.com. You can see your reports right away.
- By phone at 1-877-322-8228. Phone requests are processed within 15 days.
- By mail. Fill out the Annual Credit Report Request Form and send it to P.O. Box 105281, Atlanta, GA 30348-5281. Also processed within 15 days, though verifying your identity can take longer.
The FTC also says not to contact the three bureaus one by one for these.
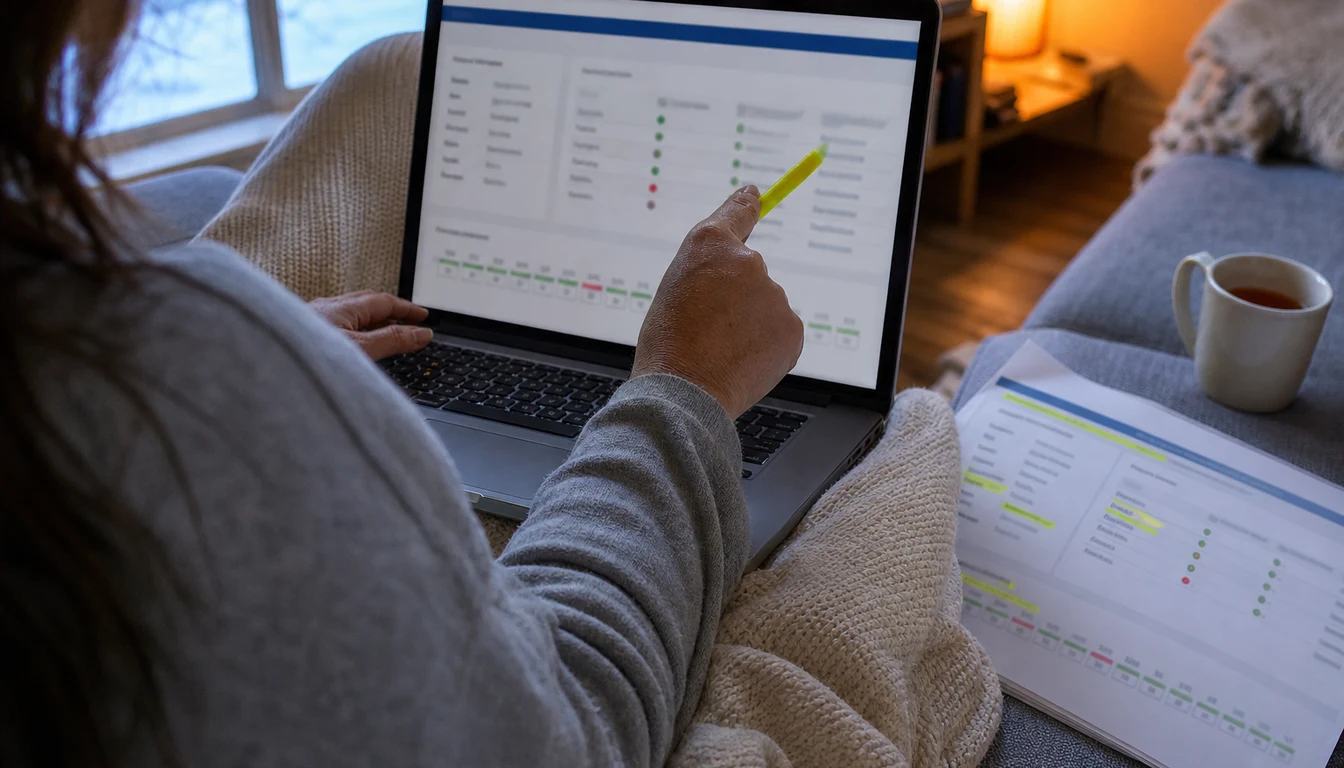
I did it online on a Sunday night with tea and a notepad. It took about 20 minutes for all three, mostly identity questions. One asked about a car loan from years earlier and I had to think hard.
How often can you get a free credit report? Every week, from all 3 bureaus
People still repeat “once a year.” That’s out of date.
Federal law gives you a free report from each bureau every 12 months, but the FTC says the bureaus have permanently extended a program that lets you check each one weekly for free at AnnualCreditReport.com. That means free credit reports from all 3 bureaus, every week if you want. I check once a month.
You may also qualify for an extra free report outside that program if:
- You got an adverse action notice (say, a denied application) and you ask within 60 days of getting it.
- You’re unemployed and plan to apply for a job within 60 days.
- You receive public assistance.
- Your report is wrong because of fraud, including identity theft, or you have a fraud alert on your file.
And checking won’t cost you points. The CFPB says requesting your own credit reports will not hurt your credit score. I needed to hear that. I’d half believed looking would make things worse.
The scariest part of my credit report was the forty seconds before it loaded.
Credit report vs. credit score: why the number isn’t in there
I opened my first report expecting a big number at the top. There wasn’t one.
Your report is the raw history. The FTC describes it as your identifying information, like your address and date of birth, plus your credit history: how you pay your bills and whether you’ve filed for bankruptcy. Your score is a number that a scoring model calculates from that history.
Think of the report as ingredients and the score as one recipe. There are a lot of recipes. The CFPB says you have more than one score, since scores can use different bureaus’ data, get calculated at different times, and vary by loan type. A few slightly different numbers is normal.
If you want a score without paying, the CFPB lists a few places to look:
- Your credit card or lender. Many show a score on your monthly statement or when you log in.
- A nonprofit credit or housing counselor. HUD-trained counselors can often give you a free report and score and go over them with you.
Mine was sitting in my card’s app the whole time. I’d scrolled past it for two years.
Curious how yours compares? I broke down the average credit score by age.
How to read your free credit report line by line
Each bureau formats things differently, but they cover the same ground. I printed mine and went through them with a highlighter, top to bottom, in this order.
Personal information. Name spellings, addresses, birth date, employers. This is where I found my first error: an apartment I never lived in, one number off from my real one. It was most likely a typo. I fixed it anyway, because a strange address can also be the first sign that someone else is using your information.
Accounts. Every card, loan and line of credit. Check that each is yours, plus its status, balance and limit. My second error was here. A store card I’d closed was still showing as open.
Payment history. Usually a grid of months with late marks. My $35 store card slip from when I was 22, the one I missed during a move, was right there. It was accurate, so I left it alone. Accurate negative info isn’t an error, even if it stings.
Collections and public records. Debts sent to collectors and things like bankruptcies. The CFPB says most negative information can be reported for seven years, and bankruptcies for up to ten.
Inquiries. A list of who has pulled your report. Look for names you don’t recognize, especially ones tied to applications you never made.
It was far less dramatic than the version in my head. Mostly accounts I already knew about.
How to dispute an error, step by step
Fixing an error usually means contacting the bureau and the company that reported it (the CFPB calls that company the “furnisher”). I followed the CFPB’s guide to disputing a credit report error:
- Mark the error. Circle or highlight it on a copy of the report. Note the account number.
- Gather proof. A statement, a closing letter, a lease. Send copies, never originals, and keep copies of everything.
- Dispute with the bureau showing the error. All three take disputes online or by phone. By mail, include your name, address, phone, each error with its account number, why it’s wrong, and a request to fix or remove it. Certified mail with a return receipt proves it arrived.
- Dispute with the furnisher too. Write to the address on your report or the company’s dispute address. Furnishers generally must respond within 30 days of getting it.
- Watch for the results. The FTC says the bureau has 30 days to investigate and must give you the results in writing. If your report changes, you get a free copy that doesn’t count as your annual one.
- If it isn’t fixed, escalate. Ask for a statement of your dispute to be added to your file, or submit a complaint to the CFPB.
The CFPB lists these numbers for disputes: Equifax (866) 349-5191, Experian (888) 397-3742, TransUnion (800) 916-8800. It also has sample letters.
My two fixes were small. I filed both online. The closed card updated fast. The apartment number took longer, and I had to mail a copy of my lease.
One note: if the error looks like identity theft, like an account you never opened, the CFPB points you to IdentityTheft.gov first.
Credit freezes and fraud alerts, the two free locks
Your report shows what already happened. A freeze or fraud alert helps with what comes next, and per the FTC, both are free.
- Credit freeze. It costs nothing to place or lift, doesn’t affect your score, and stays on until you lift it. You have to contact all three bureaus yourself.
- Fraud alert. Lasts one year and can be renewed. You contact one bureau and it has to tell the other two.
- Extended fraud alert. Lasts seven years, but it’s only for people with an FTC identity theft report or a police report.
I froze all three after that weird apartment showed up. It took about fifteen minutes. When I applied for an apartment the next year, I lifted it for the application and put it back.
Cozy tip: Put “check one credit report” on the same day every month, right next to your bill check. I pair it with my monthly money date and the free budget printable, and it takes ten minutes with a cup of tea. One report a month is enough to start.
Which “free” sites are really upsells
The FTC warns that some sites pose as AnnualCreditReport.com, use misspelled web addresses, or advertise “free” reports, scores or monitoring.
The CFPB says some free credit score services make their money from ads, while others sell scores or bundle them into paid subscriptions. A “free trial” can roll into a monthly fee.
When I see “free credit monitoring” now, I ask three things before I type anything in:
- Does it want a card number? If a free thing needs a credit card, it’s probably a trial.
- Is the URL exactly AnnualCreditReport.com? Type it yourself instead of clicking an ad.
- Did it find you, or did you find it? The FTC says AnnualCreditReport.com and the bureaus won’t email you asking for your Social Security number or account details. An unsolicited email, pop-up or call like that is probably a scam.
The weekly reports already work as a kind of DIY monitoring if you look at them. I never paid for monitoring during my payoff years. If you want a paid service, read the after-trial price first.
If you feel behind on all this, my roundup of budgeting statistics shows you’re in good company.
A section-by-section checklist for your report
The table I wish I’d had that first Sunday. It works with any bureau’s layout.
| Report section | What to check | Red flag | What I’d do |
|---|---|---|---|
| Personal info | Name spellings, addresses, birth date | An address you never lived at | Dispute it, then think about a freeze |
| Open accounts | Every card and loan is yours | An account you never opened | Go to IdentityTheft.gov first |
| Closed accounts | Status says closed | A closed card listed as open | Dispute with the bureau and the card company |
| Balances and limits | Close to your last statement | In this example: a $1,000 limit card showing $640 when you owe $40 | Check the reporting date first, then dispute if it’s still wrong |
| Payment history | Late marks match real late payments | A late mark for a month you paid on time | Send your bank record as proof |
| Collections and public records | You recognize each one | A debt that isn’t yours or is past the reporting limit | Dispute and keep copies of everything |
| Inquiries | Every name ties to something you applied for | A lender you’ve never heard of | Treat it like a fraud sign and freeze |
Common free credit report mistakes
- Paying for something that’s already free. If a site wants a card for your report, close the tab and go to AnnualCreditReport.com instead.
- Checking only one bureau. Each bureau keeps its own report, and mine didn’t match. The closed card showed up wrong on only one of the three.
- Disputing accurate information. A real late payment isn’t an error. The bureau can reject disputes it sees as frivolous, and the time is better spent on the lines that are wrong.
If your report is thin or you’re starting over, my guide to how to build credit from scratch covers the first 90 days, and the rest lives in my building credit section.
Frequently Asked Questions
Is AnnualCreditReport.com really free?
Yes. It’s the central site the FTC points to for Equifax, Experian and TransUnion reports, and you can check each one weekly. If a site asks for a credit card to show your report, it isn’t the official one.
Does checking my own credit report lower my score?
No. The CFPB says requesting your own credit reports will not hurt your credit score.
Why isn’t my credit score on my free credit report?
A report is your credit history, and a score is a number calculated from it. You have more than one score depending on the model and bureau. Many card companies show one on your statement or in their app.
How long does a credit report dispute take?
The FTC says the credit bureau has 30 days to investigate a dispute and must give you the results in writing. If your report changes, you get a free copy.
Should I freeze my credit?
It’s free to place and lift a freeze, it doesn’t affect your score, and it stays on until you lift it. You contact all three bureaus and lift it when you apply for new credit. I froze mine after finding an address I never lived at, and I’d do it again.
Grab my free Monthly Budget Template
The same cozy spreadsheet I use to track every dollar — sinking funds, bills, and savings, all in one place. Join the newsletter and I’ll send it straight to your inbox.
No spam, ever. Unsubscribe anytime. — Nora
Keep reading — more on Building Credit